Operator diligence for buyers
Before you buy, see it clearly.
Financial due diligence stops at the trial balance.
We start below it.
The accounts can be right and the business still not be what you are paying for. Welcome to Brightmere.
Nobody has to be hiding anything. The ledger records every sale correctly. It just cannot tell you which customers come back, which jobs lose money, or whether the operation can carry the plan in the information memorandum.
Before you buy a £5-50m business, we rebuild its revenue, margin, cash and capacity from its own orders, invoices and jobs, and show you where the data room story and the transactions part ways. Alongside your financial due diligence, not instead of it.

For buyers.
Before you sign, know whether the business underneath the numbers is the one you are paying for: which customers stay, which jobs make money, how much cash it really needs.
Who we work with →For advisers.
Bring us in as a workstream on a live deal, alongside the financial due diligence firm. We report to the buyer and work to the deal timetable.
Advisers and lenders →For lenders.
Your reliance comes from the financial due diligence firm. What you want from us is the evidence underneath, and that is in the memo.
Read the FAQ →What we check
Six questions the price depends on, answered from the target's own records.
Who leads the work
Most people who can read a P&L can't pull apart millions of transaction lines. Diligence below the trial balance needs both.
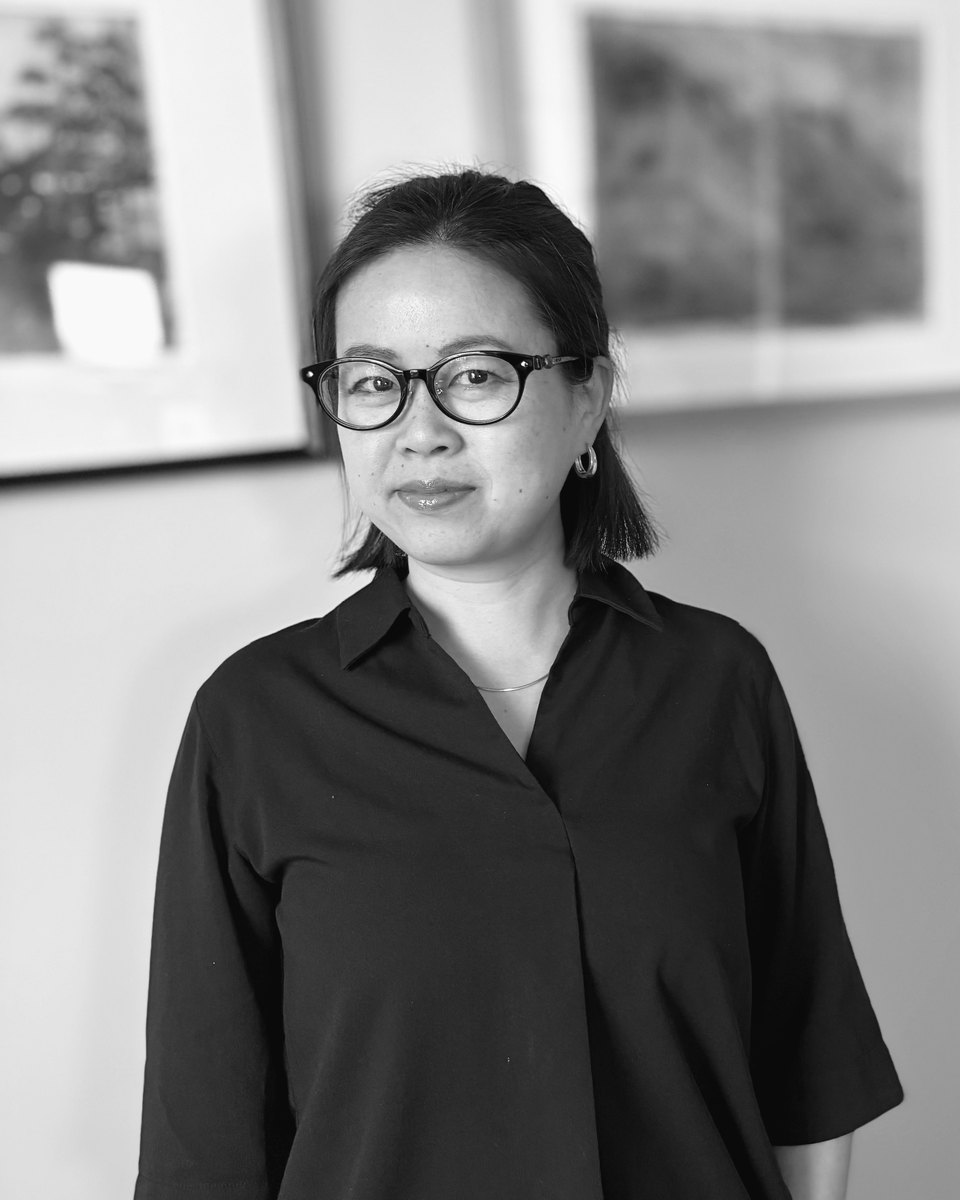
Lu Luo trained in accounting and economics, started out in accounting and corporate finance, then spent years in data science and engineering building the systems finance teams report from. Lu founded Brightmere and leads every engagement from London: scoping it, reviewing every finding and walking you through the results.

Operator diligence
What we check, how it runs, the fee
Discover more →
Questions, answered
Reliance, QoE, the working capital peg, data, timing
Read the FAQ →